Keeping crime out, so honest money moves.
Verifying customers, screening payments and keeping records are how a money app earns the right to exist. Here is how tazdan does it — and what it means for you.
These are controls built into tazdan’s software. They aren’t legal advice, don’t describe a licensed activity and don’t imply any regulatory approval.
What it means for you.
Most of this runs quietly in the background. When it does touch you, this is why.
“Why do they need my ID?”
The law requires it — and it keeps stolen identities and mule accounts away from the people you pay.
“Will every payment be held up?”
Checks run automatically before money leaves. A payment waits only when something about it is unusual.
“What if they ask where my money came from?”
For larger transfers abroad we may ask — a payslip, bank statement or business papers, for example. Answering quickly is the fastest way through.
“What happens to my money while they look?”
It stays reserved, not lost. A transfer abroad refunded before payout comes back in full, fee included.
Verification, one level at a time.
Each level unlocks higher limits. The app shows your live limits and what the next level unlocks.
- 0Not verified
Explore the app and send small amounts. Withdrawals stay locked until you verify.
- 1Level 1 · Identity
An ID document and a selfie holding it.
- 2Level 2 · Address
Proof of address — a utility bill or bank statement from the last three months.
- 3Level 3 · Source of funds
A payslip, bank statement or business papers. The highest limits.
Per-payment, daily and monthly limits are shown before you confirm, with the date they reset — daily at midnight and monthly on the 1st, Tripoli time.
Documents are reviewed by our verification team and every decision is recorded. Applying for a higher level never lowers the one you have.
Business accounts go through KYB. Payouts stay off until compliance approves, and the owner is told the outcome.
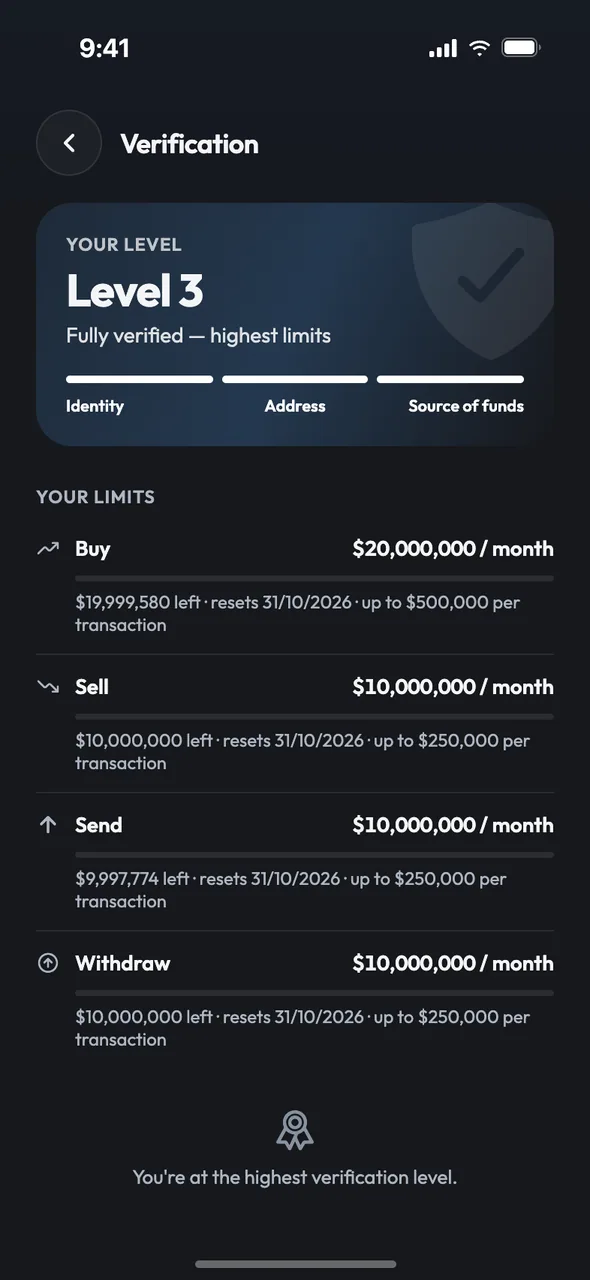
Screens from the current app build. Names and amounts are illustrative.
Checked against the lists that matter.
Before money leaves tazdan, the people and wallets involved are checked against sanctions and politically exposed person watchlists.
Who is checked
You, when you send money abroad or withdraw; beneficiaries when they’re added and again over time; businesses and the people they pay; and crypto destination addresses.
How matching works
Names are compared after removing accents, honorifics and Arabic spelling variants, checked against aliases, and weighed with date of birth and country. Wallet addresses must match exactly.
A person decides
A possible match is reviewed by our compliance team. Similar-looking names never trigger an automatic rejection.
Restricted countries
Transfers abroad and business payouts involving restricted jurisdictions are refused.
Lists with a source
Official lists — such as the UN, US, EU and UK sanctions lists — are loaded by our compliance team, with the source and date of each import kept.
Seventeen rules, before money moves.
A risk engine checks every withdrawal, transfer abroad and business payout in real time — before it runs, not after.
What the rules look for
Seventeen rules in four groups. We don’t publish thresholds — that would only help the people they’re meant to stop. Rule changes are versioned and logged with a reason.
Payments involving restricted jurisdictions.
A possible watchlist match, or no list coverage for a check.
Large amounts, sudden bursts, amounts split to stay under limits, money cycled straight back out, missing source of funds, and a combined risk score.
Brand-new beneficiaries and accounts, one payout account shared by many senders, new or shared devices, and recent password or two-factor changes.
What can happen next.
Every decision is stored with the rules it triggered and a plain-language explanation for our team.
Nothing unusual — the payment goes ahead.
A step-up check, for example a larger payment from a new device.
The money stays reserved while a person looks, or we ask you for more information.
The payment doesn’t go ahead and a case is opened. If a rule ever fails to run, the payment is held for a person — it’s never waved through.
Every flag reaches a person.
A held payment opens a case. Nobody’s account is decided by a rule alone.
An owner and a deadline
Each case has a priority and a deadline — from 4 hours for the most urgent to 7 days for routine ones.
A case file that can’t be rewritten
Notes and decisions are append-only, and a case can’t be closed without a written resolution.
The right people, and only them
Compliance and AML-analyst roles handle cases; a read-only auditor role can review everything without changing anything.
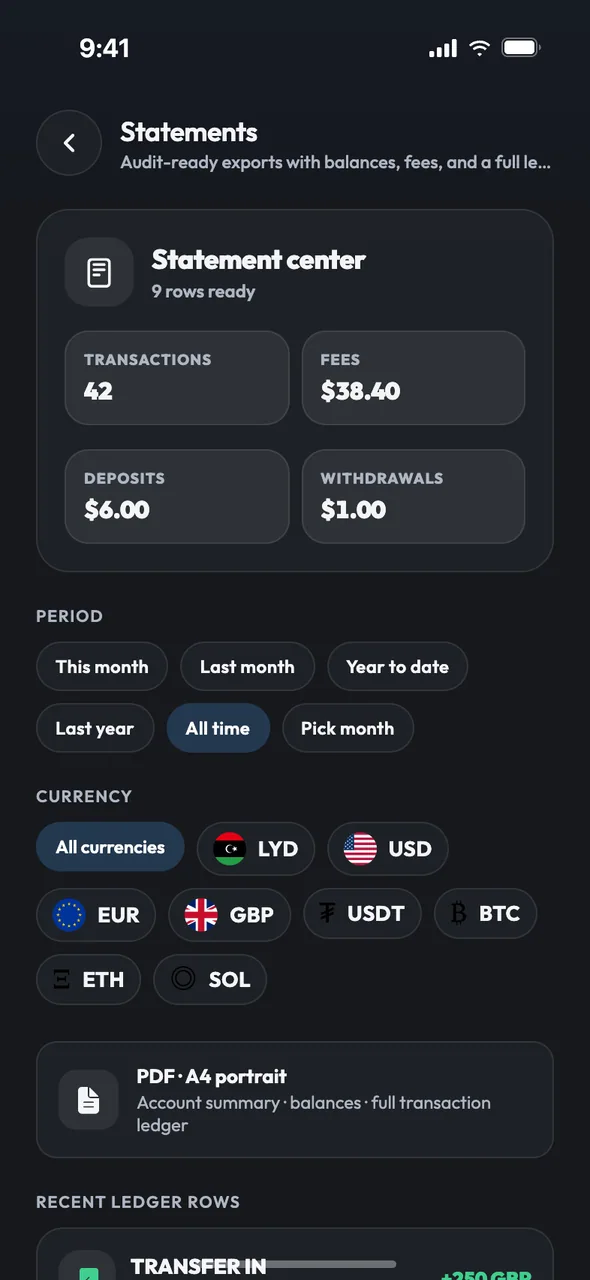
Screens from the current app build. Names and amounts are illustrative.
Records that can’t be rewritten.
The evidence an auditor or regulator needs is kept from the first day — and you can download your own statements any time.
Ledger entries, status changes, staff actions, risk decisions, case notes and security events are protected by the database against edits and deletion.
A quote for a transfer abroad can’t be changed after it’s issued.
Financial-crime rules require some records to be kept even after an account closes. Our Privacy Policy and account deletion page explain what we keep and for how long.
Who sends, who receives, and why.
Every transfer abroad carries the information a payout partner and a regulator expect to see.
- A verified sender
- Sent from a verified tazdan account, within that account’s limits, after a step-up check where needed.
- A checked beneficiary
- Bank details are validated (IBANs by checksum) and the beneficiary is screened when added.
- A purpose, and source of funds when needed
- Each transfer records its purpose; above a corridor’s threshold, we ask where the money came from.
- A locked, recorded price
- The quote you accept is kept unchanged with the transfer, alongside every status change.
Send abroad is a pilot on sandbox rails: no real money leaves tazdan until a licensed payout partner is live for each corridor.
Not built yet.
Some parts of a full compliance programme come with the licensed operating company. This is where they stand.
- Regulatory reportingPlanned
- Filing suspicious-activity reports with the relevant financial intelligence unit will be set up with the licensed entity. The evidence is already kept in cases and logs.
- Travel-rule messagingPlanned
- Exchanging sender and beneficiary details directly with partner institutions isn’t built yet.
- Periodic re-verificationPlanned
- Scheduled re-checks of customers and tracking of document expiry are planned.
- Written AML programme and compliance officerIn progress
- A programme is drafted; its adoption and the appointment of a money-laundering reporting officer come with the licensed entity.
- LicensingIn progress
- Engaging with the Central Bank of Libya on licensing. tazdan is not licensed yet.
If you’re worried about fraud, financial crime or a compliance issue involving tazdan or another user, contact us. Reports are handled confidentially.
Compliance, answered.
Technical description of controls implemented in software. It is not legal advice, does not describe a licensed activity and implies no regulatory approval.
Honest money, moving freely.
Join the waitlist and be among the first in when tazdan opens in Libya.
Pre-launch. Services depend on regulatory approval and partner availability.