Money only moves as far as the rails beneath it.
A money app is only as trustworthy as the licence and the banks behind it. tazdan is building on licensed rails, one market at a time — and this page shows exactly where each relationship stands.
Pre-launch. Nothing on this page is a licence or an approval — it’s an honest account of where we are.
Without the right rails, money gets stuck.
Most of what goes wrong with money in Libya isn’t the app on your phone. It’s what sits underneath it.
Your money leaves one bank and sits in limbo for days before it reaches another — and nobody can tell you where it is.
Direct relationships with Libyan banks are how deposits and payouts can land in your own account, with a reference you can follow.
Your card is declined the moment you pay for something abroad — a booking, a course, a subscription you actually need.
A card-issuing programme on a global network is how a card funded from your own balance could work wherever that network is accepted.
There’s no regulated way to hold digital dollars — just a stranger, an envelope of cash and a promise.
Regulated on-ramp and liquidity partners are what make buying USDT an ordinary, accountable transaction, where it’s permitted.
Money apps appear, take deposits and vanish — because nobody ever licensed them.
That’s why we’re pursuing licensing first: an app you can hold to account, with a supervisor behind it.
Every relationship, exactly as it is.
Three stages, from the licence everything rests on to the partners we’re still evaluating. No logos, no borrowed credibility — just the status, and what has to happen next.
- 01
Licensing
The permission to operate — the ground everything else is built on.
Central Bank of Libya
In progressLicensing. Our application is in preparation.
What it would mean for youAn independent supervisor over how your money is held, moved and reported — and the standing to connect properly with Libyan banks.
What has to happen nextComplete our licensing application, file it, and work through the central bank’s review.
- 02
Banking
Local rails, so dinars move between tazdan and your own bank.
Libyan banks
In discussionLibyan commercial banks for dinar deposits, settlement and payouts to local accounts.
What it would mean for youTop up from your own bank account and withdraw back to it in dinars, with transfers matched by reference instead of chased by phone.
What has to happen nextConversations are open. Next: agree terms, open settlement accounts and connect deposits and payouts.
- 03
Pipeline
Global partners we’re evaluating for cards, top-ups and exchange. Most will need our licensing in place first.
Visa
In pipelineA card-issuing programme on the Visa network.
What it would mean for youVirtual and physical cards funded from your tazdan balance, for paying online and abroad wherever Visa is accepted. Cards are designed into the app and stay off until then.
What has to happen nextLine up a licensed issuer to run the programme, then complete Visa’s programme review.
Banxa
In pipelineA fiat on- and off-ramp: card and bank top-ups into digital assets, and back.
What it would mean for youTop up by card or bank transfer and buy digital dollars like USDT in one step — or cash out the other way — where it’s permitted.
What has to happen nextFinish our evaluation, complete their partner onboarding and confirm where the service is permitted for our customers.
Crypto.com
In pipelineLiquidity and execution behind exchange.
What it would mean for youDeep liquidity from an established exchange behind every buy and sell in the app, so your orders are executed against a real market.
What has to happen nextFinish our evaluation, complete institutional onboarding and connect order execution to the app.
Names are trademarks of their owners and are shown as plain text, not logos. Listing a company here does not, by itself, mean an agreement is in place or that it endorses tazdan.
Statuses reflect where things stood on the review date above and will change as work moves on. Nothing on this page is a licence, an approval or an offer of regulated services.
The app is built. The rails come next.
Some of this already works in the app; some is built and switched off. Partners are what take each one the rest of the way.
“I made the transfer on Sunday. It’s Thursday, and I still can’t see it.”
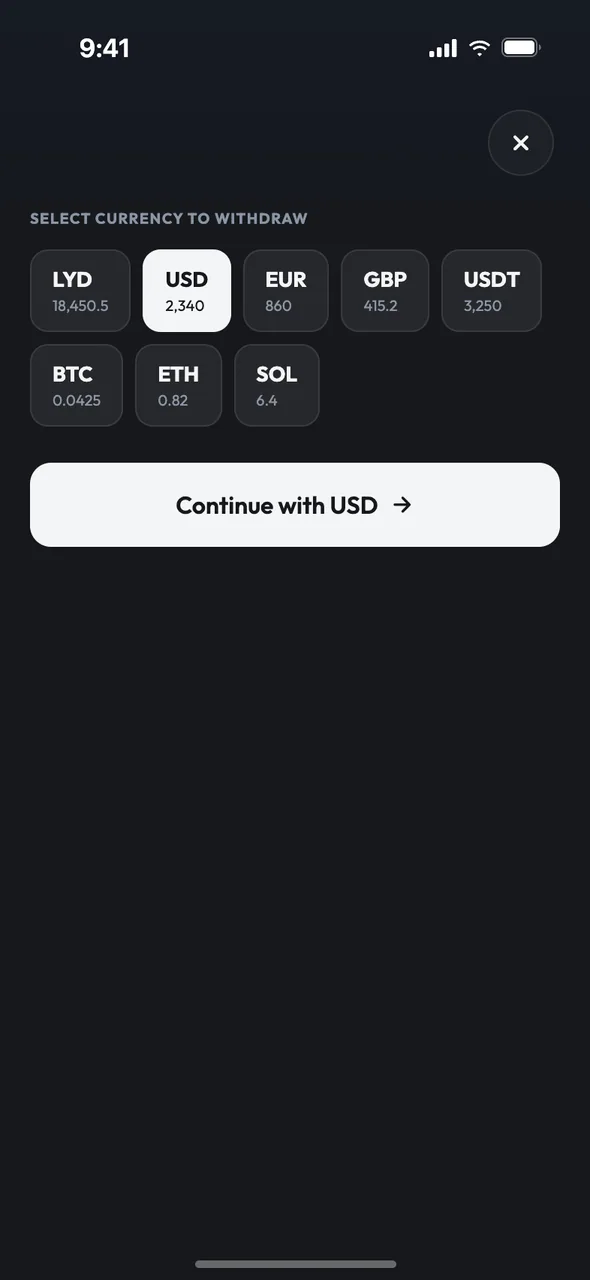
Bank transfers today. Direct bank links next.
The app already takes top-ups by bank transfer to a tazdan account, and withdrawals to your own bank — each one checked and confirmed by our team. Links with Libyan banks are how that becomes automatic matching and faster payouts.
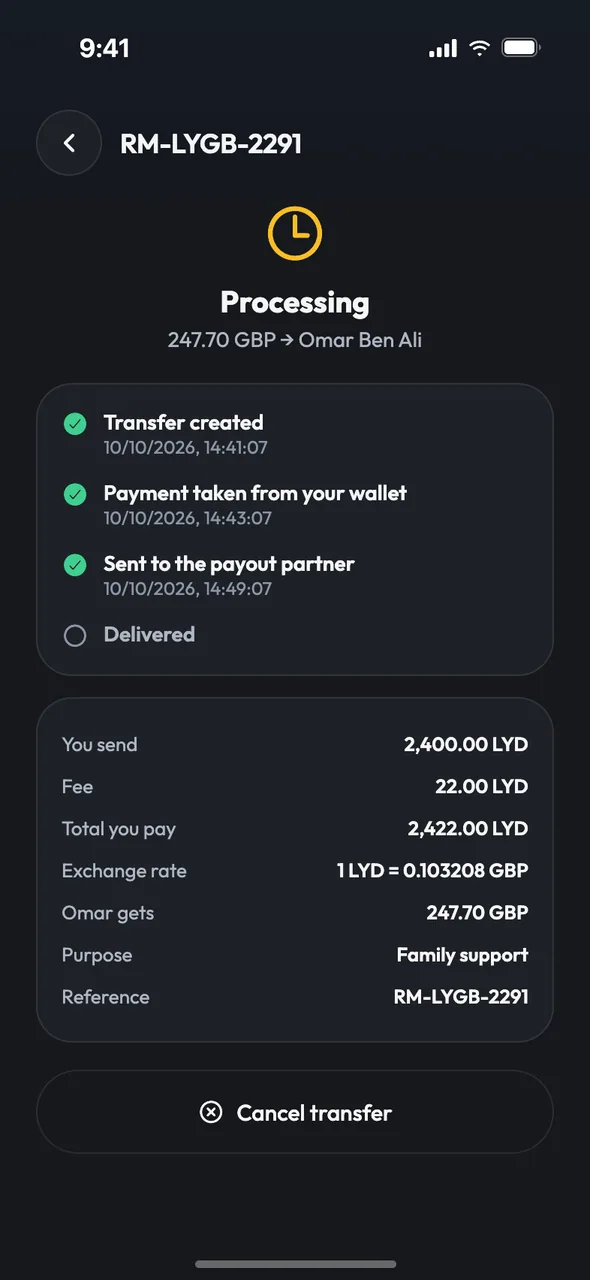
Money from family abroad goes through a middleman, takes a week, and arrives short.
Twelve corridors, tested end to end.
Locked quotes, compliance checks, tracking and refunds all run today on sandbox rails. A corridor goes live only when a licensed payout partner serves it — not a day before.
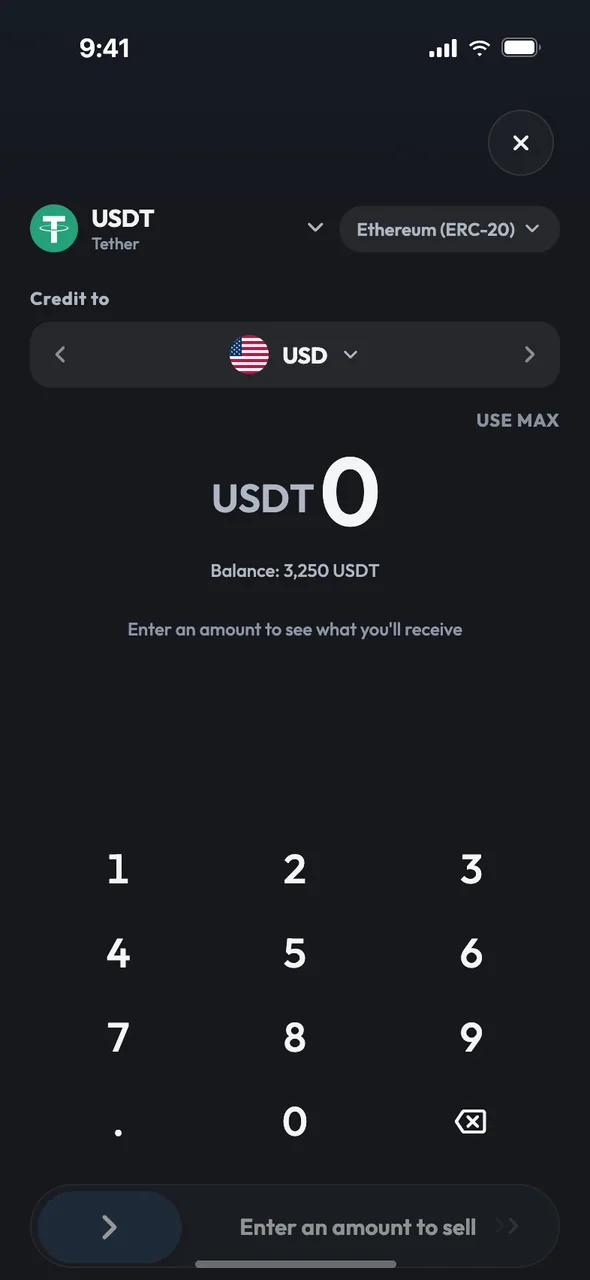
Buying dollars means meeting a stranger with cash and hoping the other half of the deal arrives.
Buy USDT in the open.
Buy and sell USDT at live prices, with every step on the ledger and nothing handed over on a street corner. On-ramp and liquidity partners are how card top-ups and deeper markets could follow, where permitted.
Screens from the current app build. Names and amounts are illustrative.
One bar, for every partner.
Global name or local bank, a partner only gets near your money if it clears all six.
Licensed where they operate
Authorised by the regulator in every market they serve. No licence, no integration.
Present where it matters
Real people and real accounts in Libya, or in the corridor they serve — not a mailbox and a website.
Customer money kept apart
Customer funds held separately from the partner’s own, so your money is never part of someone else’s balance sheet.
Sanctions and AML to our standard
Screening and anti-money-laundering controls at least as strict as the ones we run ourselves.
Support in Arabic
When something goes wrong with your money, you shouldn’t need a translator to fix it.
Built to reconcile
Idempotent requests, signed callbacks and daily statements — so a retry never pays twice and every dinar is accounted for.
Building rails into Libya? Let’s talk.
We work with banks, payment providers, card issuers, remittance operators and liquidity venues that want to reach Libya properly. Here is what you’d be plugging into.
Dinar accounts, deposits, settlement and payouts.
Card and gateway top-ups.
Virtual and physical card programmes.
Licensed payout, corridor by corridor.
Execution and hedging for exchange.
Designed in Arabic from the first screen, available in ten languages, coming to iPhone and Android.
Identity checks with document review, verification levels and live limits before money moves — and KYB for businesses.
Double-entry, enforced by the database at commit. Customer, settlement and corporate money sit in separate fund classes and reconcile against partner statements.
Operations tooling with 12 staff roles and 49 permissions, maker-checker approvals, kill switches and an audit trail on every action.
Sanctions screening, a 17-rule risk engine and case management on transfers and withdrawals.
Adapter interfaces for payouts, cards, on-ramps and banks, with idempotency keys, signed webhooks and sandbox test suites. Your adapter replaces a sandbox rail — nothing else changes.
Be there when the rails go live.
Join the waitlist and be among the first in when tazdan opens in Libya.
Pre-launch. Services depend on regulatory approval and partner availability.