Built for the markets the banks left behind.
tazdan is a Libya-first money app: dinars, dollars and digital assets in one account, at the real rate — for everyone who is tired of empty branches, two prices for one dollar and middlemen.
Pre-launch. Libya first, MENA next.
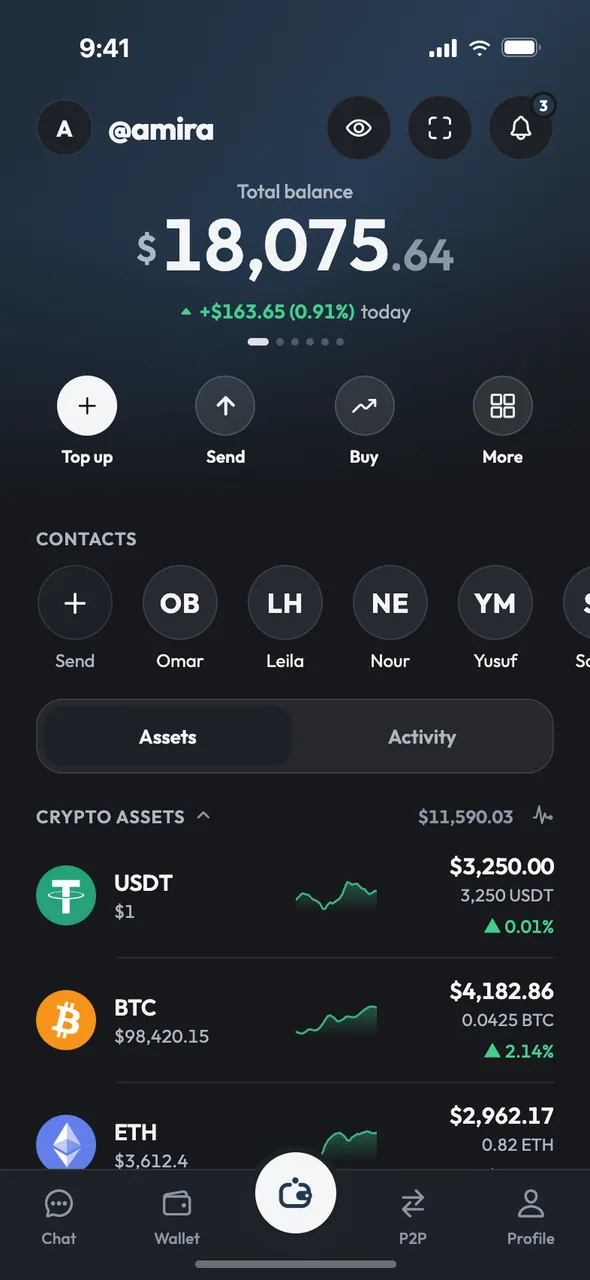
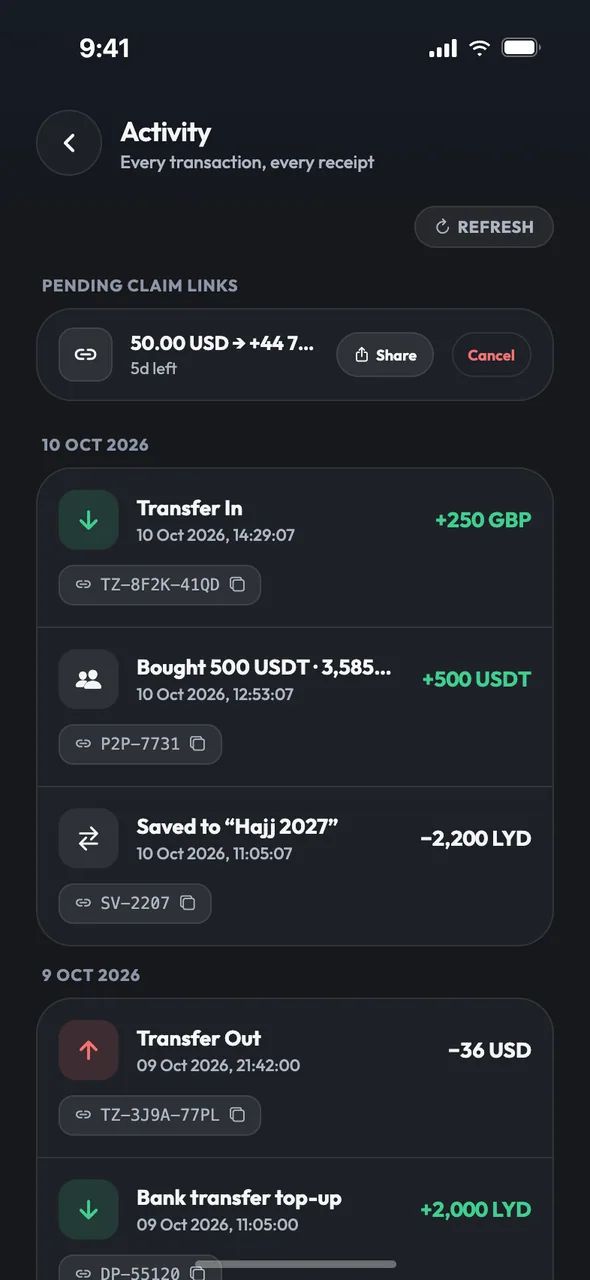
Screens from the current app build. Names and amounts are illustrative.
Money here shouldn’t be this much work.
Ask anyone in Tripoli or Benghazi about their bank and you hear the same things: no cash at the branch, a queue before the doors open, and a dollar with one price on paper and another in the market.
Families are split across borders — a son in Manchester, a sister in Istanbul, parents at home — and the money between them moves slowly, through middlemen, losing a slice at every step. The big global apps don’t serve these corridors, and the banks have mostly stopped trying.
tazdan exists to close that gap: one honest account that works here, priced at the rate people actually trade at, with the controls you’d expect from a bank.
“The bank had no cash again.”
Top up once by bank transfer, then pay and get paid from your phone.
Two dollar rates — and you get the worse one.
Prices from the live parallel-market rate, with our margin shown before you confirm.
Money from family abroad arrives late, through a middleman, with less in it.
Send-abroad corridors with a locked quote and a tracking timeline — in pilot today.
To get paid, you hand strangers your bank details and phone number.
Share an @handle or a claim link instead — no IBAN, no phone number.
Saving for something means hiding cash at home.
Savings goals that fill themselves on a schedule, and can be locked until a date.

Four promises we build around.
They decide what we ship — and what we refuse to ship.
Honest rates
We price from the live parallel-market rate and show our margin, the fee and the final amount before you confirm. A spread is never dressed up as “zero fees”.
Arabic-first
Designed in Arabic from the first screen, with right-to-left done properly — and available in ten languages.
Private by design
Pay and get paid by @handle — no IBAN or phone number changes hands. We verify who you are once, so nobody else needs to know.
Licensed rails
Where a service needs a licence, it runs with or through a licensed partner. Until that partner is live, the service stays in pilot — and we say so.
Ledger first. Features second.
Before any screen, we built the part you never see: the books. Everything else sits on top of them.
A double-entry ledger, enforced by the database at commit. Balances change only through balanced journals — no operator can edit one.
Customer money, money in transit and tazdan’s own revenue sit in separate fund classes. Money for pending operations is reserved, not spent.
If the books ever drift, trading halts automatically. Evidence tables are append-only, and every staff action records who, from where, before and after, and why.
Corrections and sensitive changes need a second person to approve them — the maker-checker rule banks use.
Large or unusual payments ask for a fresh code, or biometrics on a trusted device. Small everyday ones stay quick.
Honest about where we are.
tazdan is pre-launch. Here is what’s done, what’s happening now and what comes next.
- 01Built
Wallets, a double-entry ledger, transfers by @handle, P2P with escrow, savings goals, messaging and business tools — working in the current app build.
- 02Now
The waitlist is open. Send-abroad corridors run on sandbox rails, and we’re engaging with the Central Bank of Libya on licensing.
- 03Next — Libya
Launch in Libya with licensed partners for dinar deposits, payouts and each send-abroad corridor. Coming to iPhone and Android.
- 04Later — MENA
The same engine, corridor by corridor, as partners and approvals allow.
No dates are promised here. The waitlist hears first.
Build it with us, or tell its story.
The real rate. Finally.
Join the waitlist and be among the first in when tazdan opens in Libya.
Pre-launch. Services depend on regulatory approval and partner availability.